UAE companies that pay overseas vendors by card can get part of that spend back as corporate cashback, depending on the card and the plan behind it.
I'll cover the rules that decide how much comes back and when, using our own Pemo card for each worked example.
TL;DR
- Corporate cashback: money a card provider returns to a business as a share of its eligible card spend.
- Cashback differs from discounts: cashback accrues on settled purchases and is paid out later, unlike a merchant offer that follows one merchant's own terms.
- Some payments don't qualify: ATM withdrawals, transfers, wallet top-ups, refunds, chargebacks and disputed or unsettled transactions.
- Pemo pays on international spend: Pemo, our corporate card and spend management platform for SMEs across MENA, pays cashback on card payments to merchants outside the UAE or in a foreign currency, with AED-billed Google and Meta ads counting on accounts set up for cross-border spend.
- Rates depend on the plan: 0.5% on Starter, up to 2% on Premium and a custom rate on Enterprise, the only plan where domestic cashback is possible.
- Payouts arrive monthly: Pemo credits each month's total to the Pemo Wallet early in the following month.
- Xero records it as money received: cashback reaches the ledger as a "Receive money" transaction against the Pemo Wallet.
What is corporate cashback?
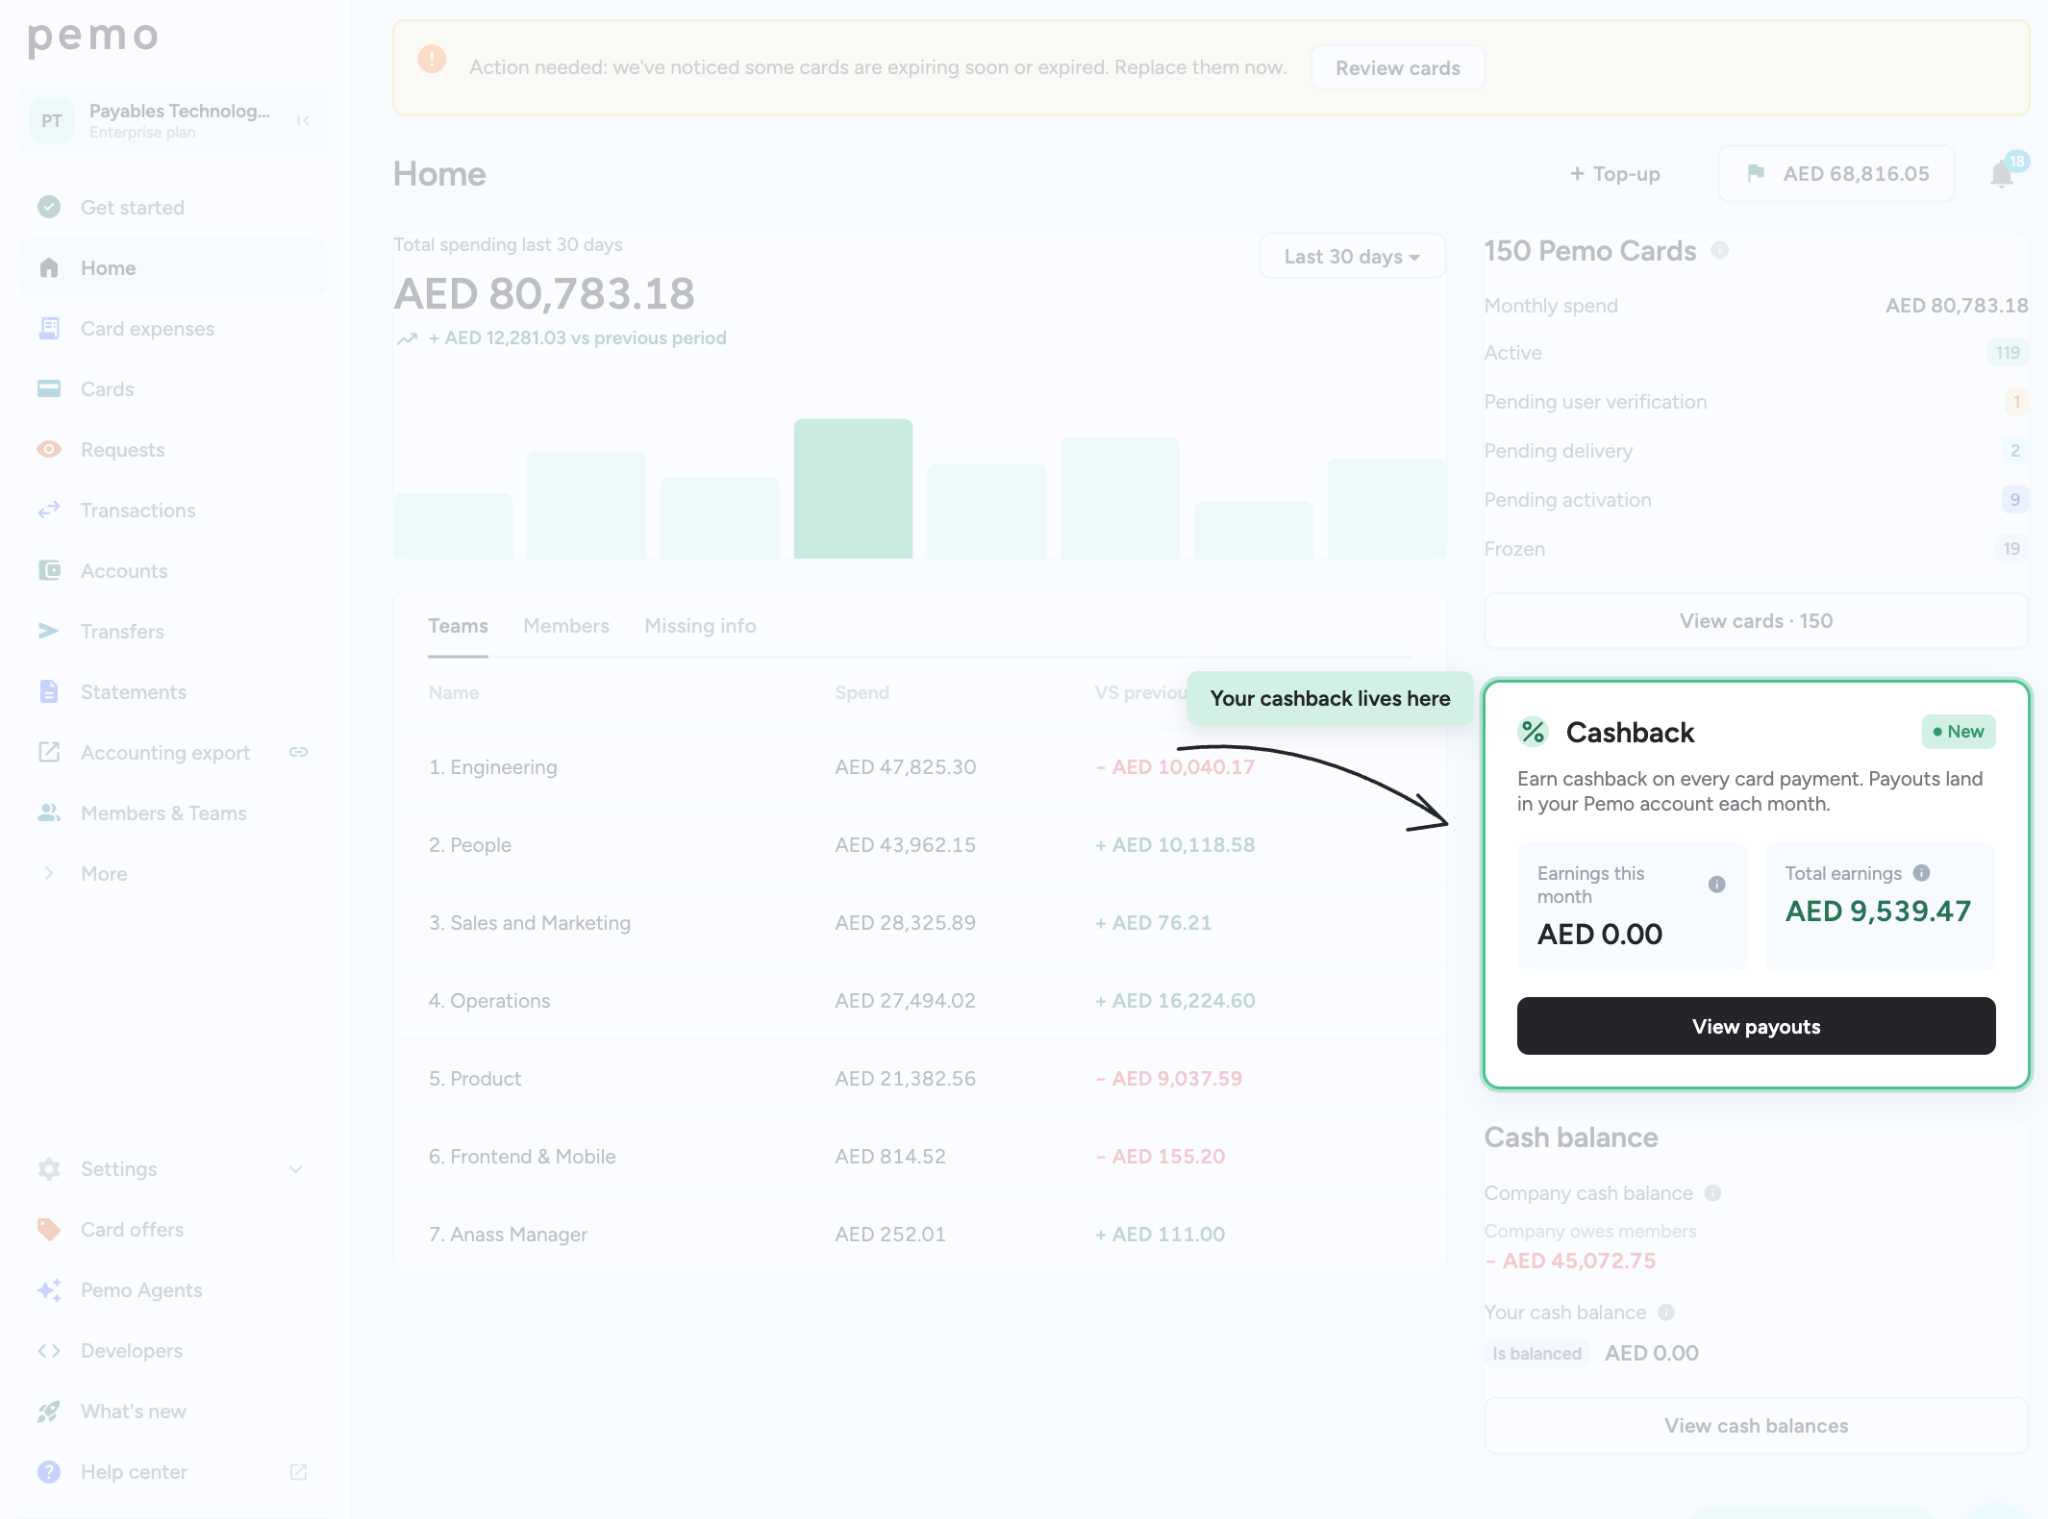
Corporate cashback is a percentage of a company's eligible card spend that the card provider returns to the business, usually as a credit to the account that funds the cards.
The money normally goes to the company, regardless of which employee made the purchase.
Each provider writes its own programme rules, deciding which merchants, currencies, transaction types and spend levels count.
Programmes tend to follow one of these models:
- Flat rate on all spend: one percentage applies to every qualifying purchase, whatever the merchant.
- Category rates: chosen merchant types, such as fuel or advertising, get more back than the base rate.
- International spend only: payments to overseas merchants or in a foreign currency qualify, the model Pemo uses on its Starter and Premium plans.
- Merchant-funded offers: a single merchant pays cashback or credit on purchases made with a particular card, often into an account held with that merchant.
Cashback isn't limited to credit cards: Pemo cards are prepaid, meaning the team spends money the company has already loaded into its Pemo Wallet.
Qualifying card payments still return cashback to that same wallet.
Prepaid cards also differ from business credit cards on liability, which our corporate card comparison covers in more detail.
Is cashback the same as a card perk or discount?
No, cashback returns a percentage of all qualifying spend and builds up as each purchase settles.
A perk or discount comes from one merchant and follows that merchant's offer terms.
For a Pemo cardholder, each kind of reward reaches the business by a different route:
For more info, see our help centre articles on earning cashback and card benefits and perks.
Here’s a sample of the Mastercard offers on Pemo's cards:
- Careem Rides: up to 30% off the next ride.
- Google Workspace: a 25% discount on the first year of Business Standard.
- DocuSign: annual plans at up to 30% off.
- HubSpot by Go Inbound: savings of up to USD 13,000 on subscription and onboarding fees, for new HubSpot customers.
- Airalo: travel eSIMs at 20% off.
- Notion: the Business plan free for six months, for startups.
Each offer carries its own terms and conditions.
Before planning a purchase around any single discount, check the live list on the card benefits page.
Software discounts fit naturally into the regular subscription review described in our SaaS spend management guide.
Which card payments count towards cashback?
On Pemo's Starter and Premium plans, the qualifying spend is international: payments to merchants based outside the UAE, or payments in a foreign currency.
Pemo's help centre gives Google and Meta ads, AWS, overseas software subscriptions and business travel as typical examples.
Behind that single rate, Pemo configures one of two components for each account:
- Cross-border spend: the payment is billed in AED, but the merchant is based outside the UAE.
- FX spend: the payment is billed in a foreign currency.
Only one of the two is active on an account at a time, which means the account's setup decides whether AED-billed payments to overseas merchants count.
Whichever one applies, the combined rate is capped at 2% and shows on the dashboard as a single figure.
Here's how the rules play out on payments a Dubai-based team might make in a month:
Ad platforms billed in AED are the payments I'd double-check first, because the AED price makes them look local.
A few transaction types don't qualify, regardless of the merchant or currency:
- ATM withdrawals: cash taken out with a Pemo card.
- Transfers: exchange house transfers, money transfers and internal transfers between wallets.
- Wallet top-ups: money the company moves into its Pemo Wallet.
- Refunds and chargebacks: money coming back to the wallet from a merchant or a dispute.
- Disputed or unsettled transactions: payments still under dispute or not yet settled.
Enterprise accounts can agree a custom rate for domestic spend, bringing UAE merchants into scope.
That plan is aimed at larger organisations, including the groups covered in our multi-entity expense management playbook.
How much cashback can a UAE business earn?
On Pemo, AED 20,000 of qualifying international card spend in a month returns AED 100 on the Starter plan and up to AED 400 on Premium.
The calculation is one multiplication: qualifying international spend times the plan's rate. Premium has no monthly limit on the amount paid back.
Each plan's advertised rate is a ceiling: the rate an account receives depends on its foreign exchange fee profile.
Companies on the same plan may therefore see small differences in their payouts.
The table below uses each plan's full advertised rate, using Pemo's plan and pricing article for the rates and the AED 399 monthly fee:
Pemo puts Premium's break-even at around AED 20,000 of monthly international spend, the level where cashback covers the plan fee.
At the full 2%, Premium returns more cashback than Starter, after its fee, once monthly international spend passes about AED 26,600.
Below that level, Premium's value lies in its multi-layer approval workflows and wider spend controls.
Companies whose KYB was approved on or after 1 July 2026 also pay a 3.68% foreign exchange fee (VAT included).
For those companies, cashback on foreign-currency spend is best weighed against that fee.
Cashback can also feed the savings reporting a finance lead already runs, using the tools in our CFO tools roundup.
When does cashback reach the company?
Pemo pays each month's cashback into the Pemo Wallet early in the following month, after reviewing that month's spend.
No one needs to file a claim or redeem anything for the payout to arrive.
For October's spend, for example, the sequence runs like this:
Pemo's support team, or the customer success manager on Premium and Enterprise, can confirm which month a plan change falls in.
Once cashback reaches the wallet, Pemo's card benefits article treats it as business funds for any company expense, with nothing to redeem and no expiry.
How is cashback recorded in the ledger?
In Xero, Pemo exports cashback as a "Receive money" transaction into the Pemo Wallet's account, the route Pemo also uses for refunds and chargebacks.
As you can see in our Xero export guide, keeping these on one route stops money coming back into the wallet from being mistaken for new expenses.
The export and payout check run in four steps:
- Open Accounting Export: go to the Accounting Export page in Pemo.
- Filter by transaction type: filter Transaction Type for refunds, cashback and chargebacks.
- Export the lines: click Export to send them to Xero.
- Match the payout: compare the amount in Xero with the dated entry under View payouts on Pemo's Cashback panel.
An AED 400 cashback payout then posts like this:
The finance team decides which account takes the credit side.
The VAT and corporate tax treatment of cashback is a question for your accountant or tax advisor.
Card fees and wallet top-ups take their own routes into Xero, mapped entry by entry in our double-entry accounting automation guide.
Teams still keying card data in by hand can start with our data entry automation guide or our accounting automation software ranking.
How can a finance team get more back from its card spend?
The first place to look is recurring international payments still made by bank transfer or on personal cards, since none of that spend returns anything to the company.
In order, the steps look like this:
- Confirm the cashback model: the Cashback panel on the Pemo dashboard shows whether the account uses the international-spend model or the legacy Essential plan, kept by some older accounts, with cashback on advertising spend.
- List recurring international payments: ad accounts, overseas SaaS, cloud hosting and international suppliers make a good starting list.
- Move those payments onto Pemo cards: a vendor switched before its next renewal counts from that renewal onwards, provided the prepaid wallet can cover the charge.
- Give each subscription its own virtual card: one card per vendor keeps renewals traceable, as our virtual corporate cards guide explains.
- Put business travel on the card: hotels and flights booked with overseas merchants qualify (travel policy is covered in our travel expense management software roundup).
- Write the card into the expense policy: a reinforced expense policy can name the company card as the default for international renewals.
I'd start with ad accounts and SaaS renewals, because they bill every month and rarely change the card once set up.
Does Pemo offer corporate cashback?
Yes, Pemo (that's us) returns cashback on qualifying international card spend on every plan: 0.5% on Starter, up to 2% on Premium and a rate agreed per company on Enterprise.
Do note that Pemo is a financial technology provider, not a bank.
NymCard Payment Services LLC issues the Pemo card and is licensed by the Central Bank of the UAE under the Retail Payment Services and Card Schemes Regulation (licence no. 08.01.02.001.2022.02).
Alongside cashback, these Pemo features help finance teams run international spend through company cards:
- Location controls: each card can be set to International, UAE only or Selected countries, on every plan.
- Instant virtual cards: virtual cards work immediately, useful when an overseas subscription moves off a personal card.
- Single-use virtual cards: a one-time card covers one payment, such as a first deposit to a new overseas supplier.
- Spend limits and merchant restrictions: limits on every plan, with merchant category restrictions from Premium upwards.
- Cashback panel: monthly accrual and dated payouts appear on one dashboard tile.
- Unlimited cards: every plan includes unlimited physical and virtual cards, billed per company.

Pemo's pricing
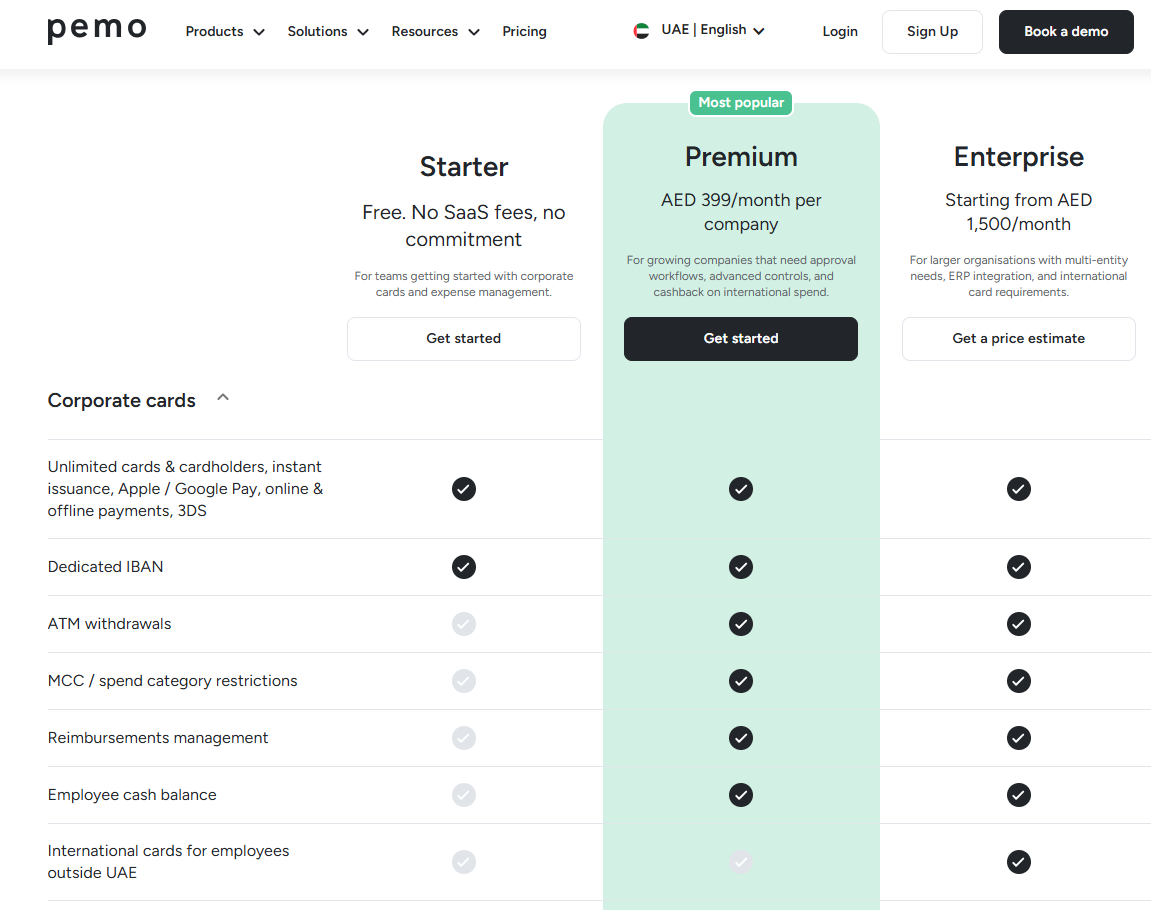
Each Pemo plan has one price per company, regardless of team size:
- Starter: free, with 0.5% cashback on international spend.
- Premium: AED 399/month per company, adding up to 2% flat, uncapped cashback on international spend, approval workflows and advanced spend controls.
- Enterprise: from AED 1,500/month, built for groups running several entities, adding custom international and domestic cashback rates, ERP integrations and cards for employees based outside the UAE.
Earn cashback with Pemo
At no cost and with 0.5% back on qualifying international card spend, Starter makes an easy first step.
After a month of recurring overseas payments running through Pemo cards, the Cashback panel shows how close the company is to Premium's break-even.
Our UAE finance stack guide shows where Pemo fits next to the ledger and payables tools.
Multi-entity groups can book a Pemo demo to get an Enterprise quote.
Corporate cashback FAQs
How should a finance team compare cashback between corporate cards?
The fairest comparison applies the same four checks to every card: what counts as qualifying spend, the rate and any cap, how and when payouts arrive, and the fees charged on that same spend.
A higher advertised rate can return less when its qualifying spend is narrower than the company's real card use.
Is corporate cashback the same as a supplier rebate?
No, a supplier rebate comes from the vendor itself, usually under a volume agreement.
Corporate cashback comes from the card provider and applies to whatever spend its programme rules count as qualifying, across many merchants.
Is cashback simpler to use than points or air miles?
In most cases, yes, because cashback has a fixed value in the company's own currency.
Points and miles vary in value with the redemption options available, which makes their real return harder to forecast.
Why choose Pemo for corporate cashback?
Pemo pays cashback on every plan, including the free Starter plan, with up to 2% flat and uncapped on Premium.
Each month's cashback reaches the Pemo Wallet automatically as business funds, with AED-billed Google and Meta ads counted on accounts set up for cross-border spend.
Mastercard savings stack on top, alongside unlimited physical and virtual cards on every plan.


